Preparation and care-team questions · Updated 4 November 2026
Prenatal Insurance Checklist: Coverage, Networks, Costs and Newborn Enrollment
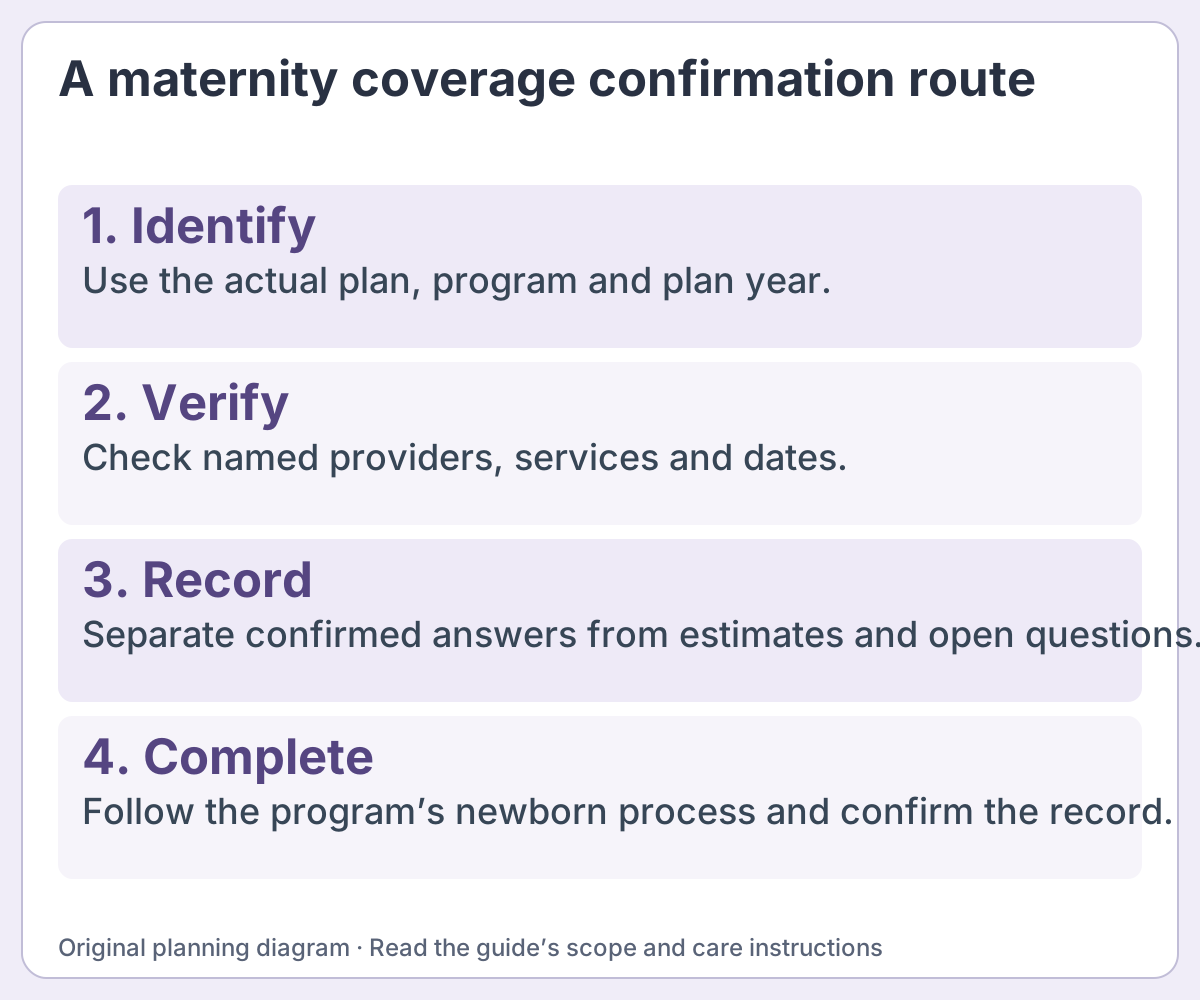
Check the actual U.S. plan, the named providers, the dates and the enrollment process. A general promise that maternity care is covered does not answer every network, cost or newborn-coverage question.
Start with this
Find the current plan documents and make one record for confirmed answers, open questions and the next administrative step. Ask about newborn enrollment before birth; use the deadline from the plan or program you actually have.
Identify the plan before asking whether maternity care is covered
This checklist is for U.S. insurance preparation. Start with the actual plan name, plan year, member information and the contact route shown on your insurance card or plan documents. An employer benefit, a Marketplace plan, Medicaid or CHIP can have different enrollment and administration processes. Advice for another country or a friend’s plan does not establish your coverage.
HealthCare.gov states that Marketplace and Medicaid plans cover pregnancy and childbirth and that maternity and newborn care are essential benefits in qualified health plans. That broad coverage statement does not tell you the cost of a particular visit, whether a chosen clinician is in network or when your own coverage starts.
Ask the plan for its current benefit documents and the appropriate person to answer maternity questions. If coverage comes through an employer, ask the benefits administrator where the plan rules and enrollment instructions are kept. Keep the source of each answer with the answer; a reassuring comment from a friend is not a benefit confirmation.
Check each provider, facility and service separately
Make a short list of the care you expect to arrange: prenatal visits, tests or scans your team discusses, the planned birth facility and postpartum follow-up. Ask the insurer about the actual clinician or organisation and the relevant service. A hospital’s participation does not answer every question about the people or services involved.
Use identifying details the plan asks for, such as the practice name, address or provider identifier, rather than relying only on a familiar hospital brand. Ask the provider’s billing office as well, and record whether the insurer’s answer matches. If two answers conflict, ask what needs to be checked before treating the issue as confirmed.
Ask about referrals, prior authorization or other plan requirements where applicable. Do not assume every prenatal appointment or scan has the same coverage status. Your care team determines which care to discuss; the insurer explains the coverage process. An insurance question should not postpone urgent medical care.
| Question | Ask the plan or billing office | What to record |
|---|---|---|
| Coverage dates | “When does my coverage start and end? Does the expected care fall within this plan year?” | Effective date, plan-year dates and any unresolved gap. |
| Provider and facility | “Are this named clinician and this facility in network for my plan?” | Exact identity checked, answer source and date. |
| Service rules | “What referral, authorization or other requirement applies to this service?” | Who completes the step and how confirmation is obtained. |
| Cost-sharing | “What deductible, copayment or coinsurance could apply?” | The relevant benefit wording and what an estimate does not include. |
| Newborn enrollment | “What must I do after birth, by which deadline, and through which process?” | Deadline, required information and how to confirm enrollment. |
Ask about likely costs without treating an estimate as a promise
A covered service can still involve amounts you pay. Ask how your plan’s deductible, copayments, coinsurance and out-of-pocket limit apply to the relevant care. Have the representative explain the terms using your actual benefit documents, including whether different rules apply to in-network and out-of-network care.
Keep premiums, the provider’s billed amount, an estimate and your eventual responsibility distinct. An estimate from one office may describe only that office’s services. Ask which clinicians, facility fees, tests or other items are included and what may be billed separately. Do not add unrelated quotes together and present the result as a guaranteed total.
If a plan year may change before birth, ask what changes at renewal: coverage dates, network participation, benefit documents and cost-sharing. A prenatal answer obtained under one plan year may need to be checked again under the next. Put “recheck after renewal” on the record if the future details are not available yet.
For an unexpected bill or a disagreement, ask the plan and provider for an explanation and the applicable review or assistance route. This checklist does not decide a claim, establish your legal protections or guarantee a billing outcome. Keep the documents you receive rather than relying only on a verbal summary.
If you have no coverage, ask about the actual enrollment route
HealthCare.gov explains that pregnancy alone does not qualify for a Special Enrollment Period through its Marketplace process, while having a baby does. Other qualifying events may allow enrollment, and Medicaid or CHIP applications can be made at any time during the year. State program rules and eligibility decisions still matter.
Use the official Marketplace or state agency for your location and ask about your circumstances without assuming that another person’s outcome applies. If you use a state-based Marketplace or a different type of coverage, confirm its own rules and dates. Open Enrollment dates, benefit processes and effective dates should come from the program you will actually use.
Ask your maternity provider about any access barrier while you clarify coverage. A useful question is “I do not yet have confirmed coverage; who can help me understand the available care and billing arrangements?” This is a request for information, not proof that a particular program will accept you or pay for a visit.
If you currently have Marketplace coverage, follow the official instructions before reporting a change. HealthCare.gov describes situations where reporting pregnancy can lead to consideration for Medicaid or CHIP and affect the Marketplace process. Do not cancel existing coverage or assume a replacement has started without confirmation from the relevant program.
Make newborn coverage a separate task
Ask before birth how the baby is added to coverage, which information will be needed and who completes the step. Care being covered for the pregnant person does not mean every enrollment task for the newborn happens automatically under every type of plan.
For the HealthCare.gov Marketplace process, the official page says to apply within 60 days after the baby’s birth when using the birth Special Enrollment Period. If you already have Marketplace coverage, it explains options for adding the baby or creating a separate enrollment group. Do not use that deadline as a promise for every employer, state program or policy.
The same official page says a newborn is automatically enrolled in Medicaid when the parent has Medicaid at birth. Confirm the applicable state process, the coverage record and how the baby’s information will be available to providers. If pregnancy-related Medicaid or CHIP coverage may end after birth, ask the state agency about the notice, end date and next enrollment options.
Give the task an owner and a reminder based on the confirmed instructions. After submitting the required information, check that the enrollment and effective date are recorded. Keep confirmation privately. A reminder marked “done” should mean the relevant step has actually been completed, not simply that you intended to make a call.
Four situations to work through
These are fictional planning examples. They illustrate a useful question or support task; they do not assess a person’s health or predict an outcome.
Example 1: The hospital is in network, but a clinician is unconfirmed
A reader has checked the planned hospital and assumes that this confirms everyone involved. They add the named practice and relevant service to the call record, then ask the insurer what identification is needed to verify each one.
They also ask the billing office what the estimate includes and what may be separate. If answers disagree, they mark the issue unresolved and ask how to obtain clarification. They do not treat a hospital directory entry as a guarantee of the final bill or delay urgent care while resolving an administrative question.
Example 2: The plan year changes before the expected birth
A reader obtains a prenatal benefit answer, but the plan renews before the expected birth. They record which plan year the answer concerns and ask when the next documents and network information can be checked.
They keep a recheck task for coverage dates, the planned clinicians and cost-sharing. A current estimate remains useful background, but it is not relabelled a promise about the next year. If an appointment or bill crosses the change, they ask the plan how it is handled rather than trying to calculate the answer from a generic example.
Example 3: An uninsured reader needs to know which options to ask about
A reader contacts the official Marketplace or state agency and asks about the available application routes and effective dates. They do not assume pregnancy by itself gives access to every Special Enrollment Period or that income alone proves eligibility.
They also tell the maternity provider about the access barrier and ask who can explain local care and billing arrangements. Any application decision belongs with the program. They keep the date, source and next step on the record and avoid cancelling other coverage based on an unconfirmed possibility.
Example 4: The baby needs coverage after birth
A family has a confirmed prenatal plan but no one has accepted the newborn enrollment task. Before birth, they ask the relevant plan or program for its exact instructions and deadline, then assign one person to complete the agreed administrative steps.
After birth, that person submits the required information through the proper route and checks the enrollment record and effective date. They do not use a generic 60-day Marketplace statement as the deadline for a different employer plan. Private identifiers and documents remain with the official process, not a public checklist or shared social-media post.
Questions readers ask
Does covered maternity care mean it is free?
A broad benefit requirement does not establish your personal cost for every provider or service. Ask about the relevant network, service rules and cost-sharing in your own plan documents. Keep any estimate’s limits visible and ask what may be billed separately.
Can I enroll because I am pregnant?
HealthCare.gov says pregnancy alone does not qualify for its Marketplace Special Enrollment Period, but birth does, and other life events may qualify. Medicaid or CHIP applications can be made throughout the year. Confirm the process and current rules with the actual Marketplace or state program you will use.
Is the newborn automatically insured?
The answer depends on the program. HealthCare.gov describes automatic newborn Medicaid enrollment when the parent has Medicaid at birth, while Marketplace coverage has enrollment actions to complete. Ask your own plan or state agency how the record is created and confirmed.
What is the deadline to add a baby?
Use the deadline confirmed by your actual plan or program. HealthCare.gov gives 60 days after birth for its birth Special Enrollment Period. Employer and other processes may differ; ask before birth, record the instructions and confirm completion after submitting the information.
Choose the next guide for your task
- Prenatal appointment preparation guides — Organise coverage, communication and care-team questions.
- Organise maternity admission documents — Keep the records and confirmations the setting requests together.
- Request an interpreter for maternity care — Prepare language-support arrangements for care discussions.
- Plan transport after maternity discharge — Confirm a practical arrangement without assuming insurance provides it.
Download the preparation sheet
Download the blank prenatal insurance call record (TXT). Keep the completed record private. It helps organise questions; it does not determine eligibility, benefits, claim payment or a guaranteed cost.
Sources and scope
This article uses HealthCare.gov’s U.S. Marketplace, Medicaid and CHIP guidance. It is an administrative question guide, not an eligibility decision, coverage determination or legal assessment. State programs, employer processes, plan documents and current official instructions govern the individual case.
Sources accessed 4 November 2026. This article is educational preparation, not an individual assessment or clinical treatment plan.